

Do you know your spouse's credit score?
Because your lender does. And when you buy a home together, you get qualified on the lower one.
I asked my wife Meg this on a walk. She laughed. Most couples I work with laugh too. Then they find out what it means for their loan.
Your lender pulls both of your scores
When you buy a home with your spouse, the lender pulls a joint credit report. That's both of you, on one report.
They don't average your scores. They don't take the higher one. They use the lower one to qualify you.
So if one of you has great credit and the other doesn't, the great score doesn't carry you. The lower score does the talking.
Each of you has three scores. Here's how the lender picks one.
This is the part most people never hear.
Each of you has three credit scores, one from each credit bureau. The lender takes the middle score from each set.
Then they look at the lower of the two middle scores. That's the score that sets your interest rate and your loan approval.
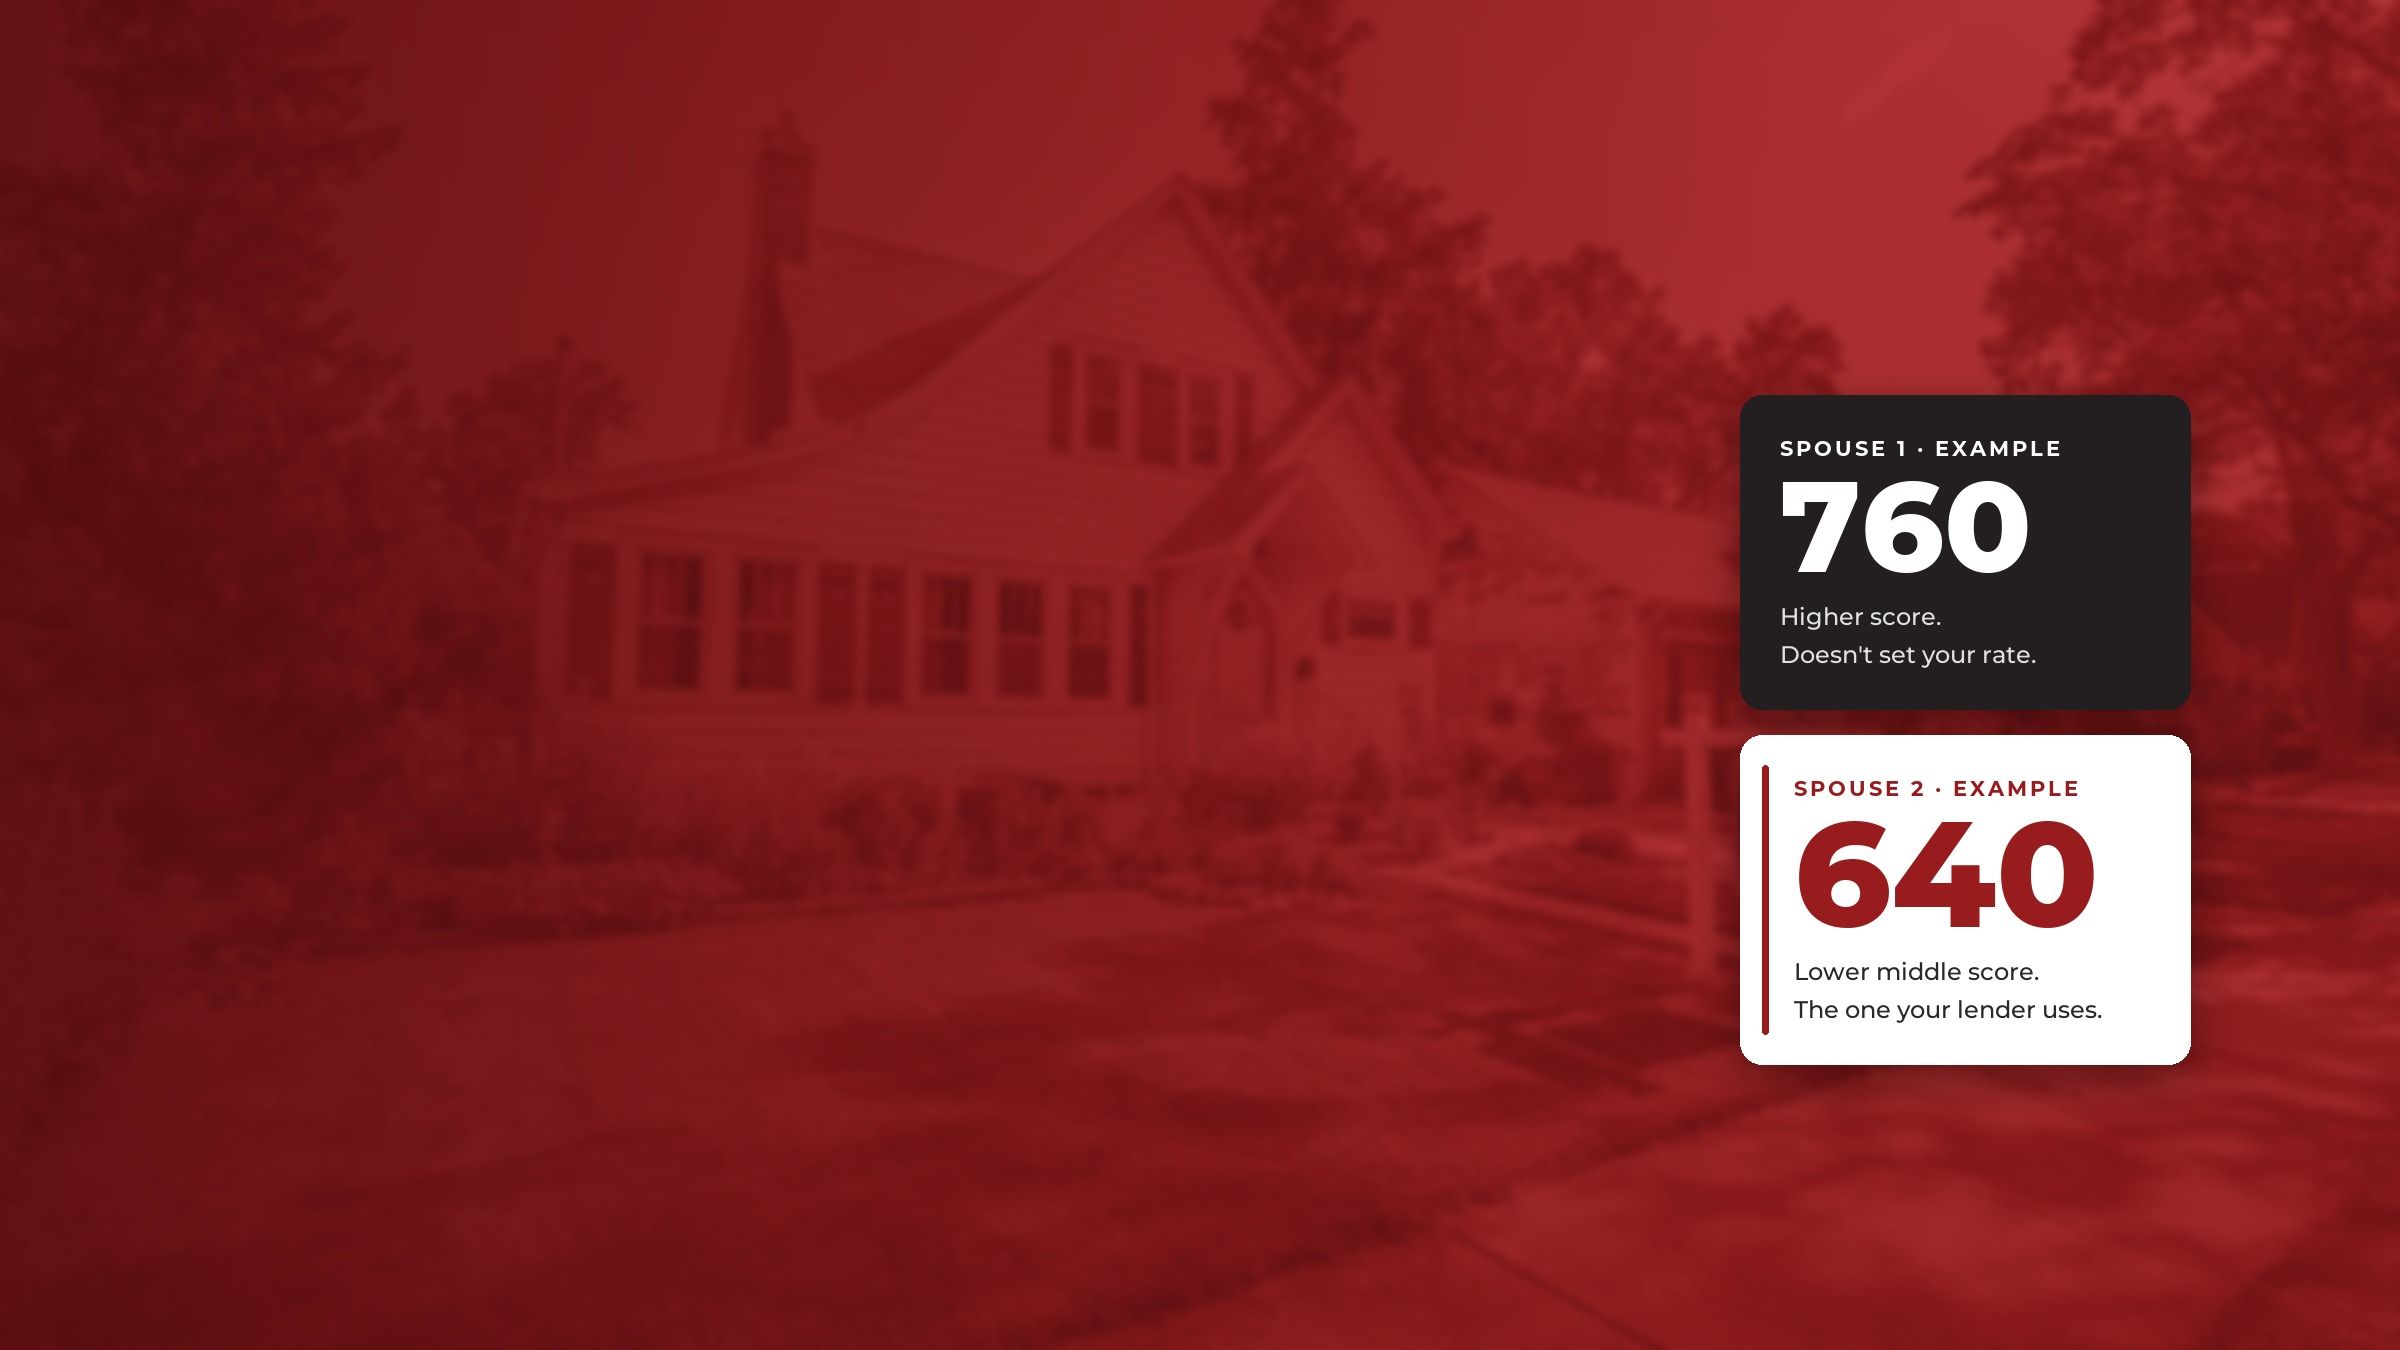
Here's a made-up example:
- Spouse 1: middle score 760
- Spouse 2: middle score 640
The lender uses 640. The 760 doesn't count toward your rate.
Free online scores are not the real score
You can get an estimated score for free online. Do it. Ask your spouse if they've checked theirs too.
But keep in mind, the scores you see on these free sites are not the score a lender will use. Lenders use mortgage scores, and those can come out different.
To get the real score, you need to talk to a loan officer.
You don't want to find a skeleton in the closet in the middle of buying a home. Find it now, while you still have time to fix it.
Fix the lower score first
The lower score is the one that counts, so that's where the work pays off.
Pay down card balances. Pay everything on time. Don't open new accounts while you're getting ready to apply.
And once you apply, freeze new credit until after closing. No new cards, no financed furniture, no car loan. The lender checks your credit again before closing.
Get the free guide: 5 Things to Do Before You Apply for a Home Loan
I put the whole list on one page, for both of you:
- Check both scores, both people
- Fix the lower score first
- Dispute errors before you apply
- Freeze new credit until after closing
- Talk to a loan officer before you apply
Download the free checklist (PDF) →
Talk to Dan Chin Homes
Thinking about buying in Madison, Middleton, or anywhere in Dane County in the next year? Let's talk before you apply, so you both know where you stand. Call or text (608) 620-4177.
Quick answers
Which credit score do lenders use for married couples?
When you apply together, the lender pulls a joint credit report. Each of you has three scores, one from each bureau. The lender takes the middle score for each of you, then uses the lower of those two middle scores to qualify you. That one score sets your rate and your approval.
Does my spouse's bad credit affect our mortgage?
Yes, if you both apply for the loan. The lender qualifies you on the lower of your two middle scores. A strong score from one spouse doesn't make up for a weak score from the other. That's why it pays to know both scores and work on the lower one first, before you apply.
Are free credit scores the same score a mortgage lender uses?
No. Free scores online are estimates. Mortgage lenders use mortgage credit scores, and those can come out different from what a free app shows you. Free scores are still a good early warning. To see the score your lender will actually use, talk to a loan officer before you apply.
What should we do before applying for a home loan together?
Check both scores, both people. Fix the lower score first by paying down card balances and paying on time. Read your reports and dispute any errors. Don't open new credit until after closing. Then talk to a loan officer with your pay stubs, tax returns, bank statements and a list of your debts.
Does the lender check our credit again before closing?
Yes. The lender re-checks credit before closing. New debt between your application and closing can change your approval. So don't open new cards, don't finance furniture and don't take out a car loan until after you close. Keep everything as steady as you can until you have the keys.
Illustrative example only. The 760 and 640 scores are made up. Your numbers will vary, and lender rules vary. This is general information, not financial or legal advice.
Questions about buying or selling in South Central Wisconsin? Let's talk it through.