
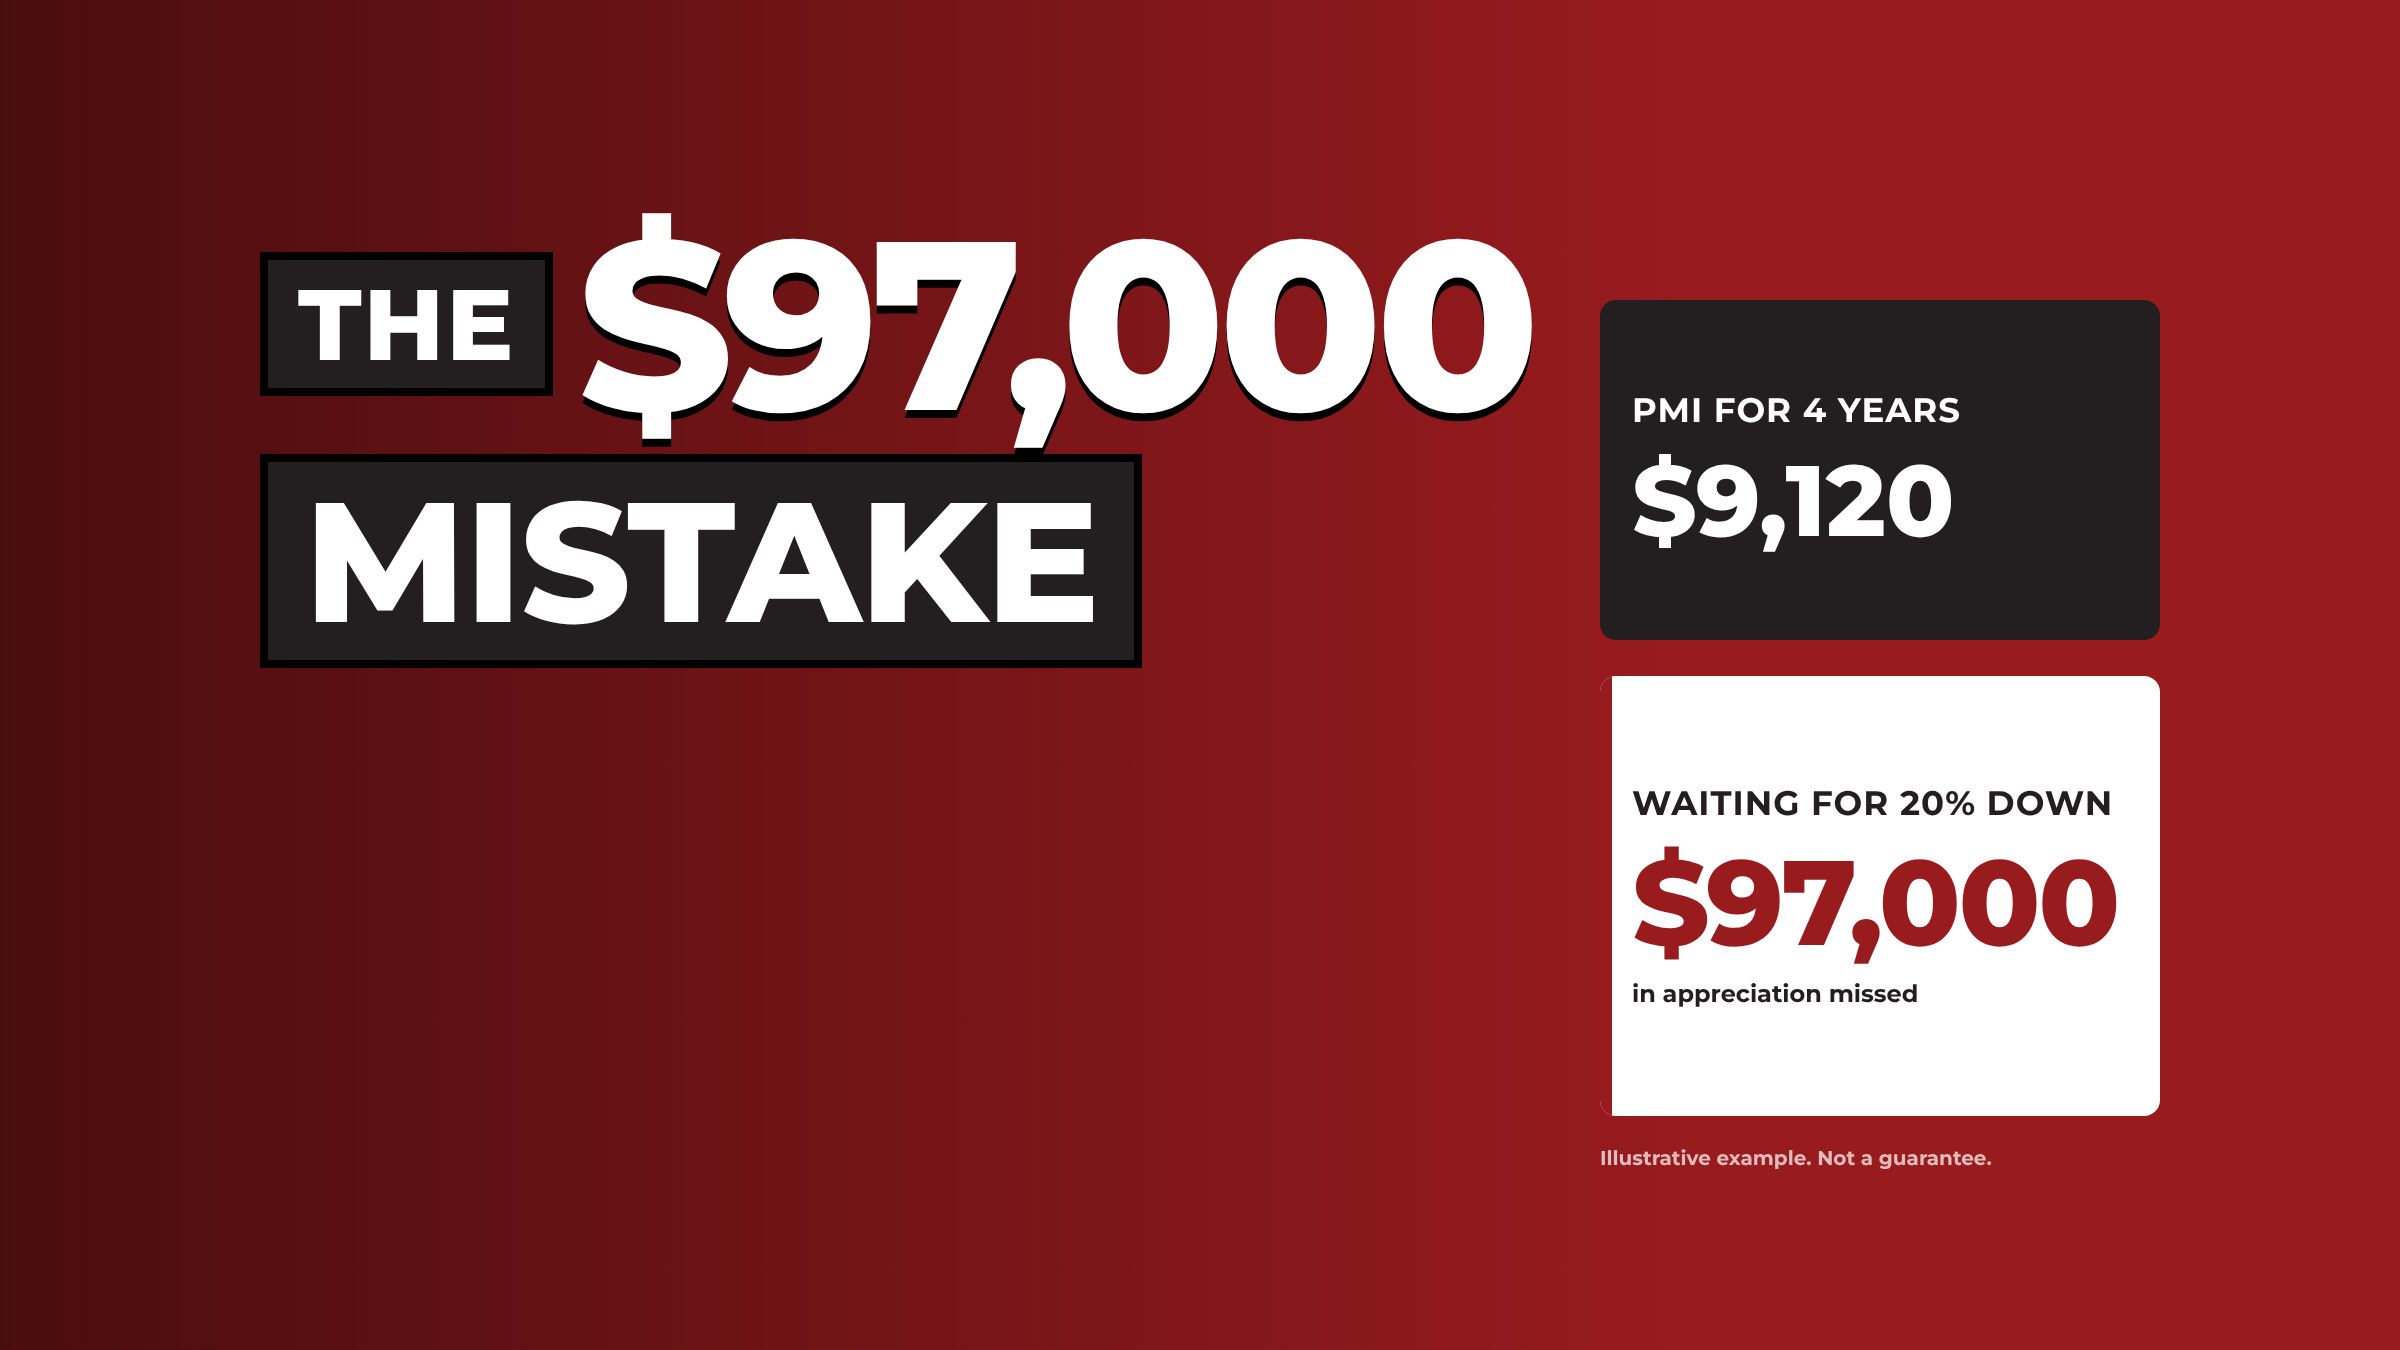

Most buyers focus on the monthly payment. And they miss the $97,000 mistake hiding in the loan terms.
Here it is. They wait to save 20% down so they don't have to pay PMI.
It feels smart. It feels safe. But when you run the math, waiting can be the most expensive choice in the whole deal.
The setup: a $450,000 house
Let's use one house for the whole example.
- Price: $450,000
- 5% down: $22,500
- 20% down: $90,000
Most people want to save the full 20% to avoid PMI. PMI is private mortgage insurance. Lenders charge it when you put down less than 20%.
So the plan is to wait and save. Let's see what that wait costs.
What PMI really costs
With good credit, PMI on this loan is about $190 a month.
You don't pay it forever. You'd typically pay it for about 4 years before you can take it off.
4 years is 48 months. 48 times $190 is $9,120.
That's the whole cost of PMI in this example. $9,120. Then it's gone.
What waiting costs
Now here's the part no one tells you.
While you spend 4 years saving up the rest of that 20%, the house doesn't sit still. It goes up in value.
At just 5% a year, that $450,000 house is worth about $547,000 after 4 years.
That's $97,000 more for the same house. You don't get that money. You pay it.
$9,120 vs $97,000
So line them up.
- Buy now with PMI: you pay about $9,120 in PMI.
- Wait 4 years for 20% down: you miss about $97,000 in appreciation.
That's paying $97,000 to avoid spending $9,120.
PMI goes away. Appreciation never comes back.
Buying sooner with PMI can be the cheaper mistake.
See the full math
Here's every number from the video in one place:
- $450,000 house, 5% down = $22,500
- $190 a month in PMI x 48 months = $9,120
- $450,000 at 5% a year for 4 years = about $547,000
- $547,000 minus $450,000 = $97,000 in appreciation missed
And if prices grow slower than 5%? The wait still costs you. At 3% a year, it's about $56,000. At 2% a year, it's about $37,000. Both are still far more than $9,120.
Nobody can promise prices will go up. But this is the bet you make when you wait for 20%.
Talk to Dan Chin Homes
Thinking about buying in Madison, Middleton, or anywhere in Dane County? Let's run your numbers before you decide to wait.
Talk to Dan Chin Homes. Call or text (608) 620-4177.
And follow me for more smart homebuying tips.
Quick answers
Is it better to wait for 20% down or buy now with PMI?
It depends on your numbers, but waiting often costs more. In this example, PMI on a $450,000 house costs about $9,120 over 4 years. Waiting those same 4 years while the house goes up 5% a year means paying about $97,000 more. PMI is a cost that ends. Missed appreciation does not come back. Run your own price, rate and down payment before you decide.
How much does PMI cost on a $450,000 house?
In this example, with good credit and 5% down, PMI is about $190 a month. Paid for about 4 years, that's $9,120 total. Your PMI depends on your credit score, your down payment and your loan type, so your number can be higher or lower. A loan officer can give you a real quote before you buy.
When does PMI go away?
On a regular conventional loan, you can usually ask your lender to remove PMI once you owe 80% of the home's original value. It drops off on its own at 78%. Paying extra on the loan gets you there sooner. Some lenders also let a new appraisal count if your home has gone up in value. Ask your lender for their exact rules.
What if home prices don't go up 5% a year?
The wait still costs money in most cases. On the same $450,000 house over 4 years, 3% a year adds about $56,000 to the price, and 2% a year adds about $37,000. Both are far more than the $9,120 in PMI. Prices would need to stay about flat for all 4 years for waiting to come out ahead.
Is the $97,000 guaranteed?
No. The $97,000 is a worked example. It assumes a $450,000 house that goes up 5% a year for 4 years. Home prices can rise slower, stay flat, or drop. Past appreciation is not a promise of future appreciation. The point is to see both costs side by side, PMI and waiting, before you choose.
Illustrative example, your numbers will vary, not financial or legal advice. The math assumes a $450,000 home, 5% down, PMI of $190 a month for 4 years, and 5% yearly appreciation. Past appreciation is not a promise.
Dan Chin Homes | Real Broker
Questions about buying or selling in South Central Wisconsin? Let's talk it through.